 Available in US
Content
What “Value” Really Means in a Cricket Price
A reader once told me they only bet on winners. I had to break the news that they would lose money long-term doing exactly that, because backing winners and finding value are completely different disciplines. Value isn’t about being right — it’s about being right more often than the price predicts.
A value bet is a stake where the true probability of an outcome is higher than the implied probability of the offered odds. If a Test outcome is 50 per cent likely and a sportsbook prices it at 11/10 — implied probability 47.6 per cent — that’s a value bet. The bookmaker is offering you a slightly longer price than the chance deserves. Over a long run of similar bets, the punter’s edge compounds.
This sounds simple in theory and is brutally hard in practice. The hard part isn’t the maths. The hard part is being correct about the true probability often enough for the edge to survive variance.
Expected Value: The Maths Behind a Value Call
Expected value (EV) is the formal expression of what I’m describing. It’s the average return per unit staked across an infinite number of identical bets. A positive EV bet is one where, over the long run, you would expect to be ahead. A negative EV bet is one where you’d expect to be behind. The maths is dry but it’s the entire foundation of serious betting analysis.
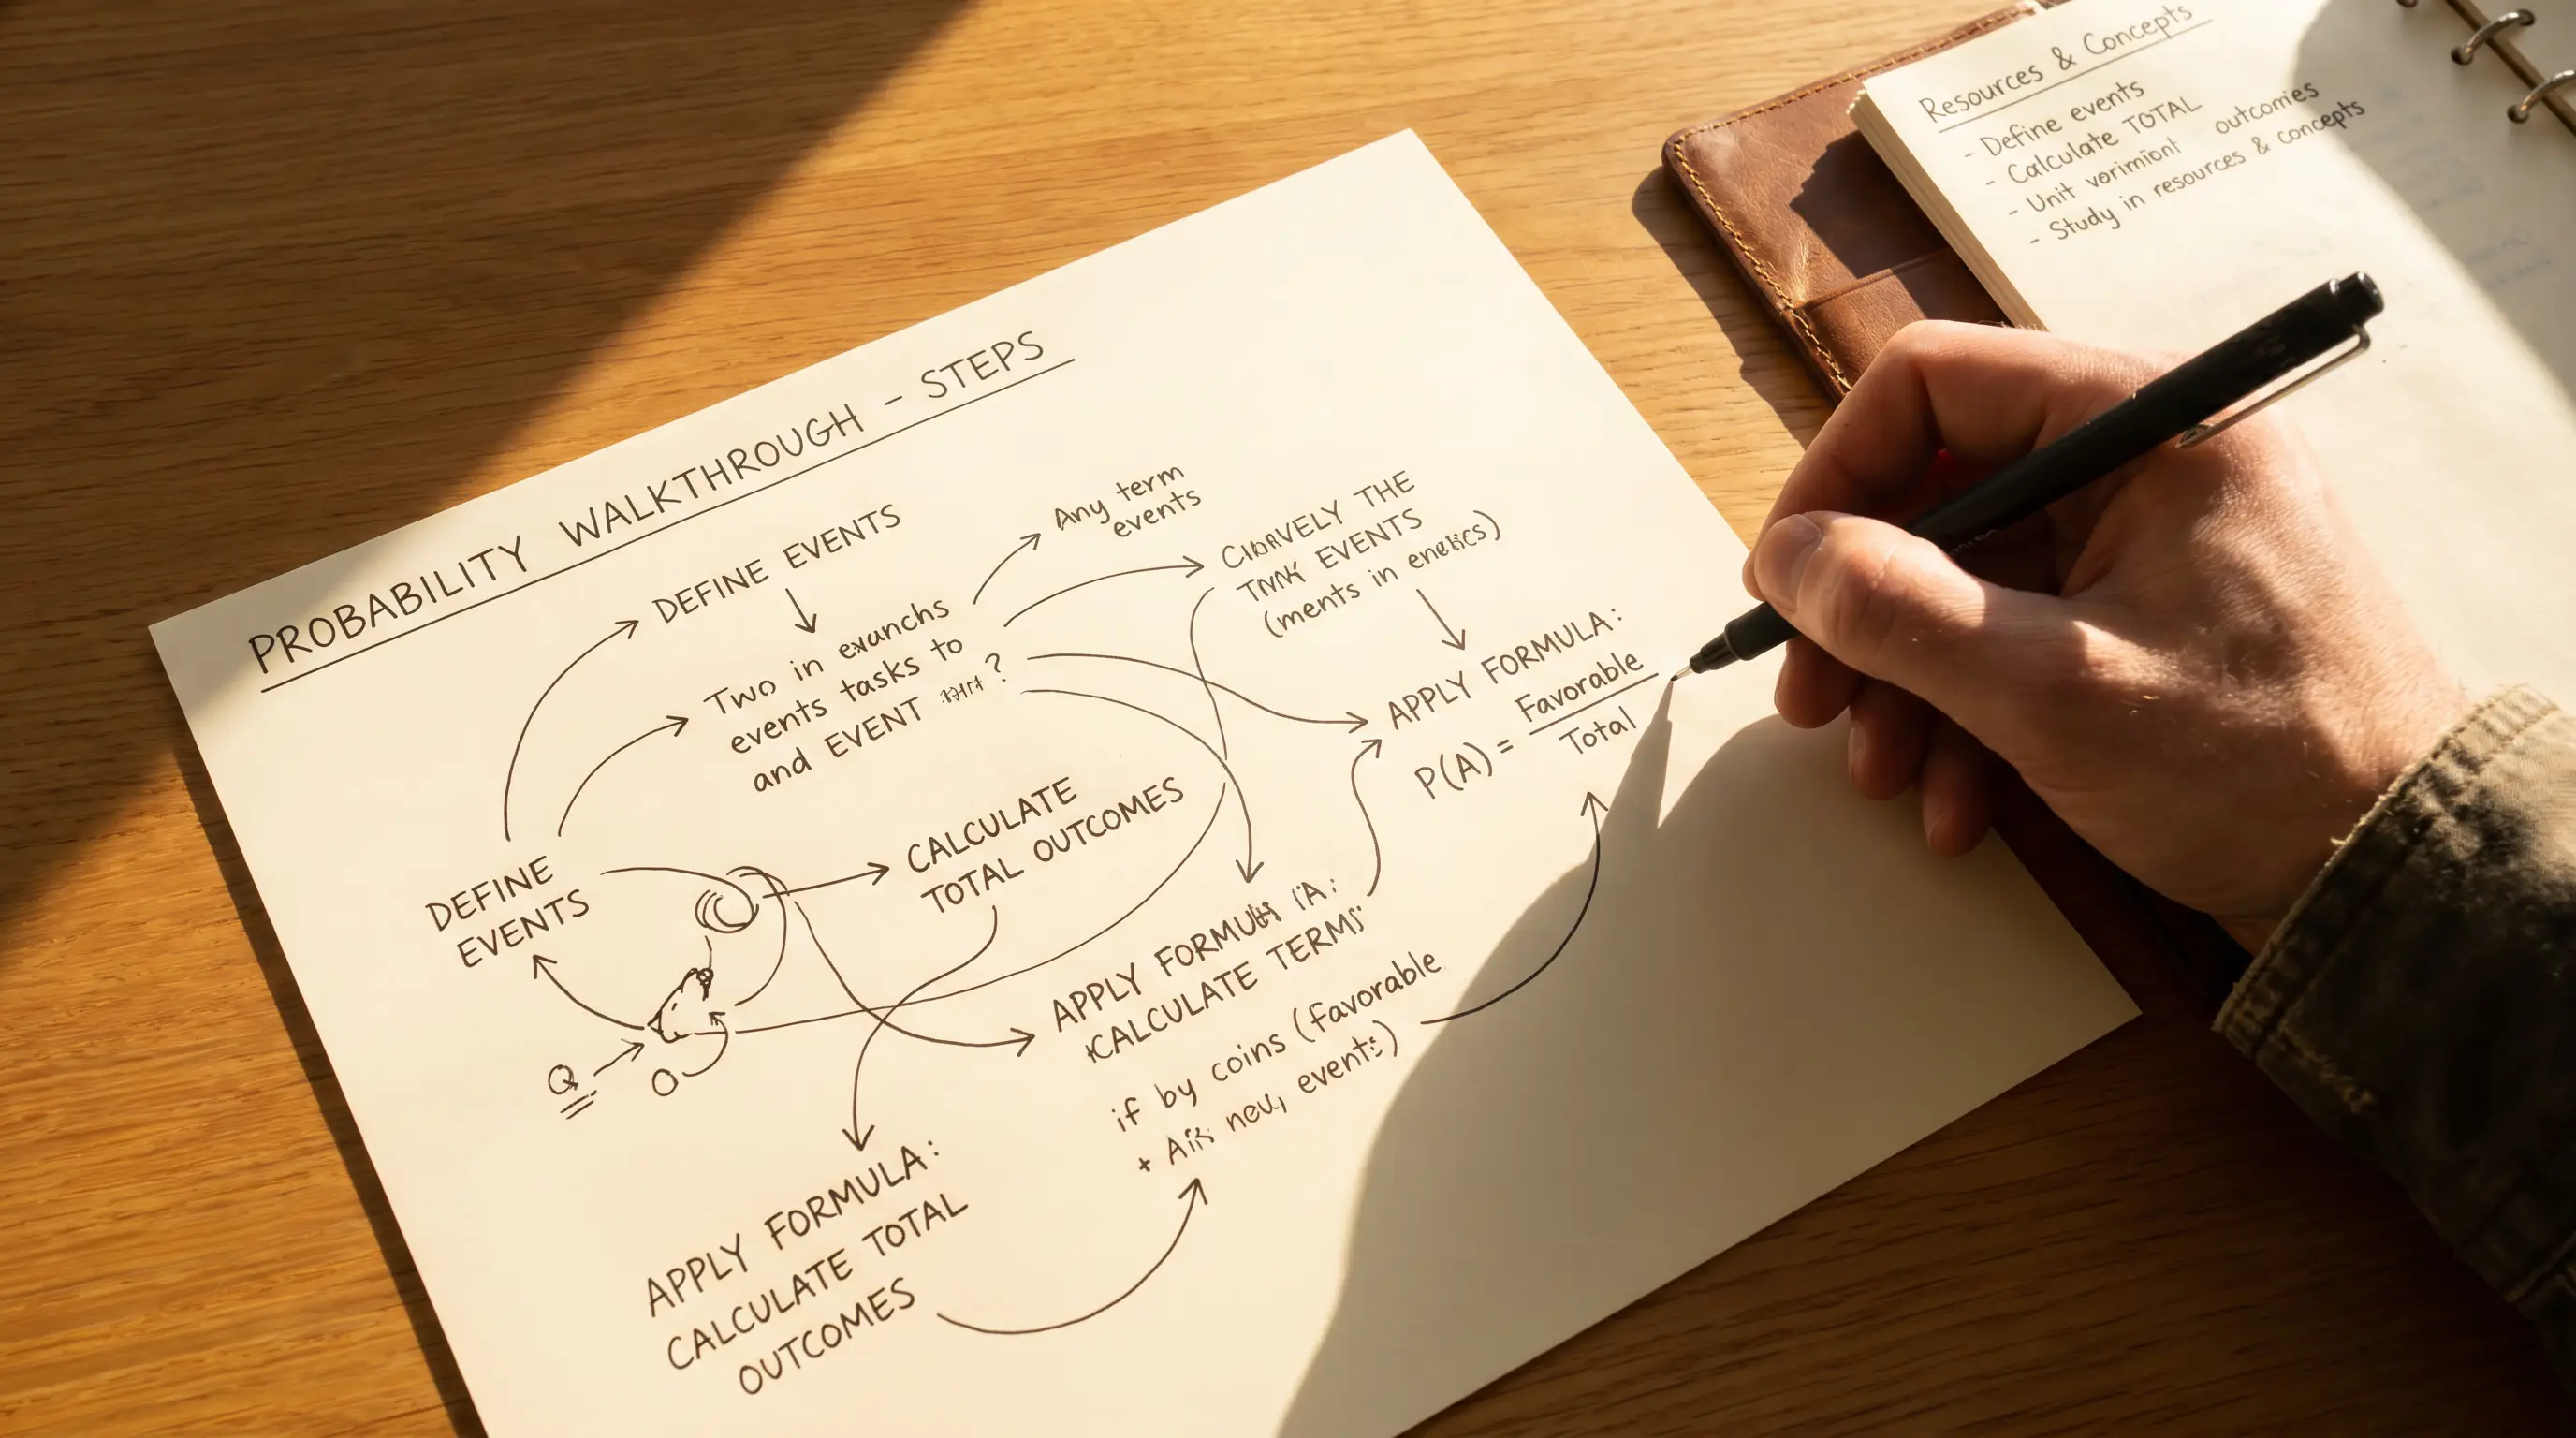
The formula is: EV equals the probability of winning multiplied by the profit per unit staked, minus the probability of losing multiplied by the stake. A simpler version: EV per unit equals (true probability × decimal odds) minus 1.
A worked example. You estimate Team A’s chance of winning a T20 at 55 per cent. The sportsbook is offering Team A at 2.10 decimal (11/10 fractional). EV per unit equals (0.55 × 2.10) minus 1, which is 1.155 minus 1, which is 0.155 — a positive 15.5 per cent expected value. Over a hundred bets at the same estimated edge, you’d expect to return 15.5 per cent ahead of stakes.
The trick — and the catch — is that the calculation depends entirely on your estimate of true probability being accurate. Garbage in, garbage out. A 55 per cent estimate that’s actually 50 per cent destroys the edge entirely. EV is only as good as the forecast feeding it, which is why I spend most of my analytical time on the probability estimate, not the EV calculation.
Markets Where Value Surfaces Most Often
Value distributes unevenly across cricket markets, and the pattern is consistent enough to guide where serious punters should spend their attention. Three categories of market produce most of the genuine value opportunities I find.
First: live in-play markets immediately after wicket events. Sportsbooks suspend pricing for a few seconds after a wicket falls and re-open at fresh odds, but the re-opening price is sometimes mis-aligned with the new match state. A team that’s just lost a top-order batter often sees their match-winner price drift wider than the actual win probability shift, because pricing engines over-react to wicket events on average.
Second: player markets in mid-tier franchise leagues. Top batter and top bowler lines in the CPL, BBL or PSL are often priced by engines that work primarily from international averages, missing local form and conditions specific to the league. The engines are blunt enough that genuine value persists across the season.
Third: outright markets early in tournaments. Pricing engines anchor heavily to pre-tournament form and ranking, and they re-adjust slowly. A team that wins its opening fixture by a wide margin sometimes shifts in the outright market less than the new probability would justify.
The integrity backdrop matters here too. IBIA recorded 300 suspicious betting alerts across all sports in 2025 — a 29 per cent rise from 219 in 2024 — and the cricket-specific share continues to grow, which means UK sportsbooks have been tightening their risk discipline on lightly traded niche markets. That tightening shows up as wider overround in those markets, and ironically, wider overround can sometimes coexist with genuine mispricing on specific selections within that overround.
False-Value Traps in Cricket
The trap I see most often is what I call “results-based bias” — a punter convinces themselves a price is value because the outcome they expect feels obvious. Feeling obvious is not the same as being underpriced.
The classic example is a strong home team in a clear mismatch fixture. The 4/9 favourite “feels” like a banker — but at 1.44 decimal, the implied probability is 69.4 per cent. To find value here, your true probability estimate has to be above 69 per cent, which is harder than it sounds. The match always has variance, and the actual hit rate of 4/9 favourites in cricket comes in closer to the implied 69 per cent than punters’ intuition suggests. Backing short-priced favourites without checking your own probability estimate is a slow leak in any bankroll.
The second trap is mistaking selection bias for skill. If you’ve backed five value calls this week and four came in, that doesn’t prove your method works — five bets is well within variance. Real edge takes hundreds of bets to demonstrate, and most punters don’t have the patience or the bankroll discipline to wait for the sample.
The third trap is data freshness. A pricing engine that was wrong yesterday may not be wrong today after it’s seen the latest match. Backing a “value” line on Tuesday that no longer represents the operator’s current pricing model means you’re trading on stale information. Always check the line is still active before staking, and refresh your own probability estimate against new data.
Tracking Value Bets Over a Season
Betting is the single most popular form of non-lottery gambling for British adults in the most recent UKGC participation data — 12 per cent of adults in the four weeks before survey, rising to 16 per cent among men. That popularity is what creates the volume that lets serious value-seekers find genuine mispricing. It’s also what makes record-keeping essential.
My personal log records every bet with the same fields: date, fixture, market, stake, displayed odds, my estimated true probability, my estimated EV percentage, and the outcome. Across a season, this log answers two questions only it can answer. First: is my probability estimation actually accurate, or am I systematically over- or under-forecasting? Second: which markets have given me a long-term positive return, and which have given me a long-term negative one?
The answers to both questions are usually uncomfortable for the first six months of serious record-keeping. The seventh month and onward is when the discipline starts producing useful feedback. For the structural protection layer around how UK sportsbook promises like best-odds-guaranteed interact with value-seeking, the BOG mechanics breakdown covers the operational details.
Value Betting Questions
Two reader questions on value betting come up repeatedly and deserve direct answers.
How many bets are needed to confirm a value edge?
The honest answer is more than most punters want to hear. To distinguish a real 5 per cent edge from random variance with reasonable statistical confidence, you typically need somewhere between 500 and 1,000 bets at consistent stake size and consistent methodology. Smaller edges need larger samples — a 2 per cent edge can take several thousand bets to confirm. Most punters draw conclusions about their method after 50 or 100 bets, which is well inside the variance band and meaningless either way. The first useful read on whether your method has edge usually comes after a full year of disciplined betting.
Can value still exist in markets with high overround?
Yes, but it is rarer and the edge has to be larger to overcome the structural margin. A market with 110 per cent overround means the displayed implied probabilities exceed true probabilities by an average of 10 percentage points across all outcomes. A value bet in that market requires your true probability estimate to be higher than the inflated implied probability — not just higher than the no-vig probability. In practice, the highest-overround cricket markets (exotic player props, niche specials) are usually best avoided for serious value work, even though individual mispricings do occur.
