 Available in US
Content
- What "UKGC-Licensed" Tells a Cricket Punter
- The Anatomy of a UKGC Remote Betting Licence
- Consumer-Facing Rules That Affect Cricket Markets
- The Integrity Network: UKGC SBIU, ICC ACU, IBIA, Sportradar
- What Suspicious Cricket Markets Look Like in Data
- Enforcement Against Illegal Operators in 2025–2026
- The Statutory Levy and How Cricket Bets Feed It
- What Licensing Costs Mean for Cricket Odds You See
- Practical Signals of a Well-Run UK Cricket Sportsbook
- Licensing and Integrity Reader Questions
What “UKGC-Licensed” Tells a Cricket Punter
“UKGC-licensed” is the most overused phrase in the UK betting industry and the least understood by the punters it is meant to reassure. The phrase appears in operator footers, in affiliate marketing, in welcome-bonus terms, and in almost no editorial content that explains what it actually means. That gap is the reason this guide exists.
The UK Gambling Commission is the statutory regulator established by the Gambling Act 2005 to license and supervise operators serving the British market. Any operator taking bets from a British resident on cricket — or anything else — must hold a UKGC remote operating licence. The licence is not a marketing claim. It is a regulatory permission, granted after a fitness test, that exposes the operator to ongoing supervision, audit, and enforcement.
The British online betting market is large enough that the licence carries real weight. UK remote betting generated £16.8 billion in gross gambling yield in 2025. That figure represents the operators’ aggregate margin across all British online betting, of which cricket is a small but visible portion. The size of the regulated market is what gives the UKGC its leverage — operators cannot afford to lose the licence, and the regulator can extract substantive behavioural compliance as a result.
For the cricket punter specifically, “UKGC-licensed” delivers several things that are invisible on the coupon: dispute resolution rights, segregation of customer funds, fixed-odds settlement guarantees, identity-verification requirements that mostly protect against money-laundering exploitation, and access to industry-wide self-exclusion through GamStop. These are not features the operator advertises because they are the regulatory floor, not a competitive differentiator. They are also the reason a UKGC-licensed sportsbook is structurally different from a non-UK operator advertising to British punters.
The Anatomy of a UKGC Remote Betting Licence
The licence itself is not a single document. It is a structured permission with conditions, codes of practice, and licence conditions that the operator must meet across its entire UK-facing operation. Understanding the structure helps the punter understand what they are entitled to and what they are not.
The headline component is the operating licence, which permits the holder to provide one or more specific gambling activities — remote betting on real events, in this case — to British residents. The licence carries an annual fee scaled to the operator’s revenue, a fitness assessment for the operator’s owners and key staff, and an audit obligation that the operator must commission and file with the regulator.
The licence conditions and codes of practice — known across the industry as the LCCP — are the rulebook the operator must comply with on a continuous basis. The LCCP covers technical standards for the betting platform, fair-terms requirements for promotional offers, anti-money-laundering controls, customer-fund segregation rules, marketing restrictions, and a substantial section on consumer protection and responsible gambling. Every change to the LCCP is consulted on publicly and applies to all licence holders.
A second component is the personal management licence, which applies to individuals in specified roles within the operator — the chief executive, the head of regulatory affairs, certain senior trading staff. These individuals are personally licensed in addition to the operator’s corporate licence, and they carry personal accountability for compliance failures. The personal licence is the structural feature that prevents senior executives from delegating regulatory responsibility downwards. The buck stops at named, licensed individuals.
The operating licence is not equivalent to a licence from Gibraltar, Malta, Curacao, or the Isle of Man. Each of those jurisdictions has its own regulatory framework, and an operator licensed in Gibraltar but not in the UK may not lawfully take bets from British residents on cricket. The practical verification — confirming that a specific operator holds a current UKGC licence rather than relying on a footer claim — is its own exercise, and I walk through the process in my piece on verifying a UKGC licence.
The licence is conditional and revocable. The regulator can suspend or revoke a licence for breach of any condition, and the enforcement history includes operators losing their UK permission and being required to wind down their British-facing operations. That is the leverage the licence creates: the operator’s UK business is at risk if compliance falls below the regulatory floor.
Consumer-Facing Rules That Affect Cricket Markets
The LCCP touches almost every interaction the cricket punter has with a UK operator. Most punters never read the document, but they are protected by it whether they know it or not. The rules that matter most for cricket betting are concentrated in five areas.
Fair-odds and settlement rules are the first. UK-licensed operators must publish their settlement rules in a place accessible to the punter and must apply those rules consistently. A bet placed at a specific price must settle at that price unless a published rule — dead heat, void, palpable error — applies. Disputes that the operator cannot resolve internally go to an alternative dispute resolution provider whose decision is binding on the operator.
Promotional fairness is the second area. Welcome bonuses, free-bet offers, acca insurance, and Best Odds Guaranteed promotions must comply with detailed fairness requirements. Wagering requirements must be clearly stated. Restrictions — minimum odds, eligible markets, maximum stake limits — must be disclosed before the punter opts in. Withdrawal of an offer mid-promotion is restricted, and operators have been fined substantially for breaches.
Identity verification is the third area, and it is the one punters notice most. UK operators must verify the identity of every customer before allowing them to withdraw funds, and increasingly before accepting deposits beyond modest thresholds. The verification is a regulatory requirement, not an operator preference. The same rules apply to source-of-funds verification for high-stake customers, and these checks can interrupt a withdrawal until the documentation is provided.
Responsible-gambling tools are the fourth area. Deposit limits, loss limits, session limits, reality checks, and self-exclusion must be available to every customer on every UK-licensed operator. GamStop — the national self-exclusion scheme — is mandatory: every UK-licensed operator must integrate with it, and a customer who self-excludes through GamStop is barred from every UK-licensed operator simultaneously.
Marketing restrictions are the fifth area. Cricket bonuses and free-bet offers cannot be marketed to customers who have self-excluded. Promotional emails must include opt-out functions. Affiliate marketing is subject to the operator’s responsibility for the affiliate’s behaviour, which has tightened sharply in recent years. The rules around marketing to under-25s are progressively restrictive, with cricket sponsorship of shirts and stadium advertising now subject to industry codes that limit visibility during family-viewing hours.
Each of these areas is enforced through audit and complaints. The cricket punter who never lodges a complaint experiences the rules as background friction. The cricket punter who does lodge a complaint experiences them as the leverage that gets the operator’s attention. Both experiences are the system working.
The Integrity Network: UKGC SBIU, ICC ACU, IBIA, Sportradar
Behind the customer-facing licence sits an integrity network designed to detect and disrupt match-fixing and related corruption in cricket. Four institutions form the backbone, and each plays a specific role that the others do not duplicate.
The UK Gambling Commission’s Sports Betting Intelligence Unit — the SBIU — is the regulator’s internal investigation team for betting-related integrity issues affecting British markets. The SBIU receives alerts from operators, sports governing bodies, and integrity associations; investigates patterns of suspicious activity; and coordinates with law enforcement where criminal investigations follow. The SBIU is the British end-point for integrity intelligence; everything else feeds into it.
The International Cricket Council’s Anti-Corruption Unit — the ACU — is the global cricket-specific integrity body. The ACU runs anti-corruption education programmes for players, monitors international cricket fixtures for irregularities, and investigates allegations of corruption involving cricketers under ICC jurisdiction. The ACU does not regulate the betting industry directly; it focuses on the sport side of the integrity equation, with the betting side handled by national regulators and industry associations.
The International Betting Integrity Association — IBIA — is a private association of regulated betting operators that pools suspicious-betting information across member books. IBIA recorded 300 suspicious betting alerts in 2025, up 29 percent from 219 in 2024. The increase reflects expansion of the regulated betting markets that IBIA covers as much as any increase in underlying corruption, but the headline number is operationally significant: IBIA is generating actionable alerts at scale, and those alerts flow to national regulators including the UKGC.
Sportradar Integrity Services is the largest commercial integrity monitor and operates the Universal Fraud Detection System, the machine-learning architecture that monitored more than one million events in 70 sports in 2025 and identified 1,116 suspicious matches across that universe. The match-fixing detection rate improved to 1 in 709 matches compared with 1 in 608 in 2024 — a statistical improvement that reflects both real reduction in fixing and improved detection capability. Sportradar’s data flows to IBIA, to national regulators, and to sports governing bodies under information-sharing agreements.
The four institutions overlap by design. Suspicious activity on a UK-licensed operator’s cricket book generates an internal alert at the operator, which triggers an IBIA filing, which feeds the UKGC SBIU and Sportradar’s monitoring system, which in turn alerts the ICC ACU if the matter involves a fixture within ICC jurisdiction. The redundancy is the integrity architecture’s principal strength.
What Suspicious Cricket Markets Look Like in Data
Cricket-specific integrity activity has grown sharply. In 2025, cricket recorded 59 suspicious matches identified by Sportradar — more than triple the count seen in earlier years since 2021 — driven by the proliferation of short-format competitions and improved AI detection by Sportradar’s UFDS. The increase is a function of detection capability and market expansion, not necessarily an increase in underlying corruption, but the operational reality is that more cricket matches are being flagged than ever before.
The UFDS itself flagged 56 percent more suspicious matches in 2025 than 2024 across all sports — the count rose from 436 to 682 — and cricket has been one of the sports where the improvement in detection has produced the largest absolute increase in flagged events. The detection mechanism looks at betting flows across the global market, identifies patterns that deviate from the model’s expected distribution, and assigns probability scores to each match. Matches above a threshold are flagged for investigation.
The patterns that flag a cricket match as suspicious are usually one or more of three signatures. The first is volume — a sudden surge in stakes on a specific market in the hours or minutes before a match, typically concentrated on one side of a binary outcome and on operators where the punters in question hold accounts. The second is correlation — multiple accounts staking simultaneously on the same selection, often through small operators or exchanges where the trail is harder to follow. The third is anomaly — an operator’s pricing engine producing a movement that is inconsistent with the betting flows it sees, suggesting that the flows are being driven by information the engine does not have.
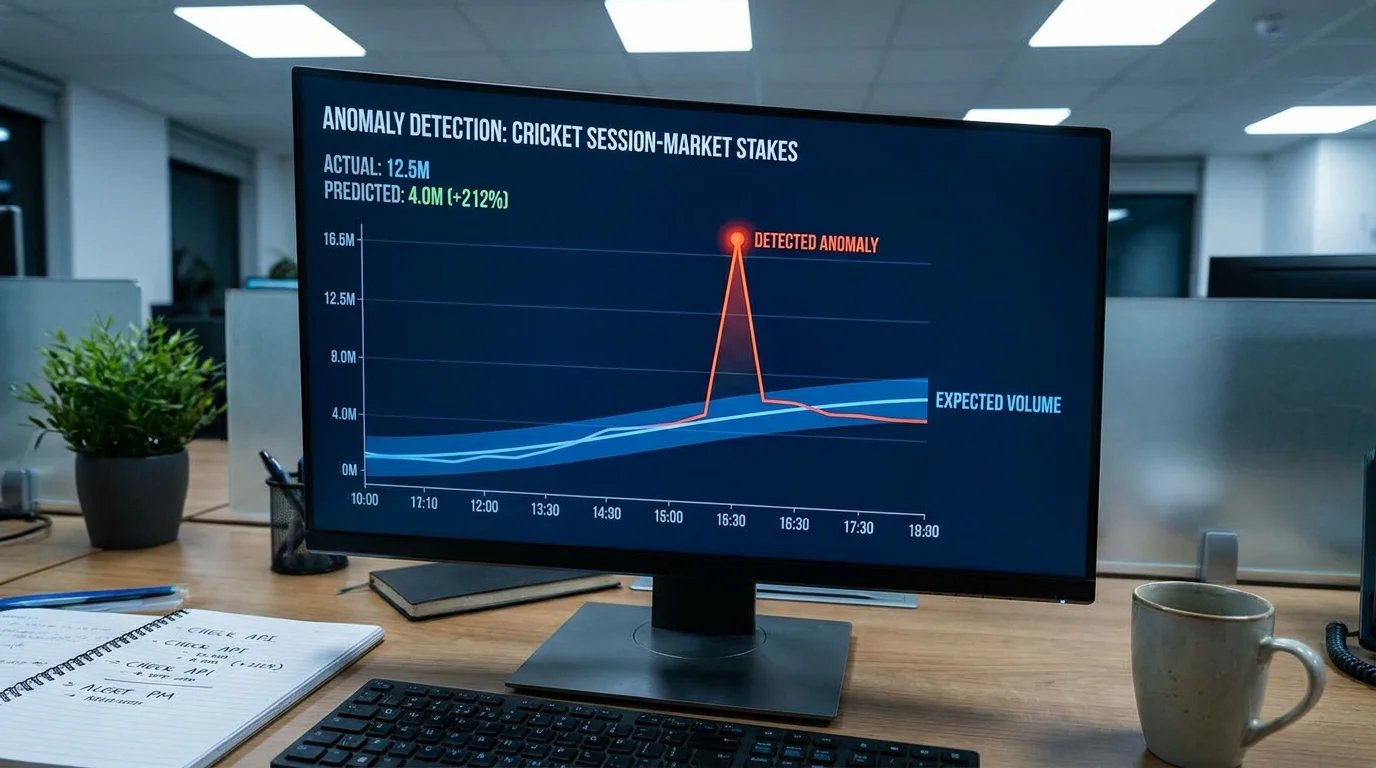
Cricket markets most commonly implicated in integrity alerts are session totals, over-runs in short-format matches, no-ball and wide markets in low-tier T20 leagues, and method-of-dismissal markets in the same lower-tier fixtures. The pattern reflects the underlying corruption mechanic: a corrupted player can manipulate the outcome of a single ball or over much more easily than the outcome of an entire match, and the markets that price single balls or overs are correspondingly more susceptible.
The fixtures flagged most often are in lower-tier T20 leagues, particularly in jurisdictions where the regulatory environment is weaker and the player-pool turnover is high. International cricket and the top franchise leagues — IPL, BBL, The Hundred — rarely appear in suspicious-match alerts at the rate that lower-tier T20 leagues do. The structural reason is that the integrity layer in top competitions is more aggressive and the financial incentives to fix top-tier matches are smaller relative to the punishment risk.
For the UK punter, the implication is direct. Markets on top-tier cricket are structurally safer than markets on lower-tier T20 cricket, and the safest cricket markets to stake on are the match-winner and team-total markets on internationals and top franchise leagues, where the integrity coverage is most rigorous.
Enforcement Against Illegal Operators in 2025–2026
Enforcement against unlicensed operators serving the UK market has accelerated sharply in the past two years. The UK Gambling Commission issued 741 cease-and-desist notices to operators and advertisers in the 2025/26 financial year, a significant increase on prior years and a signal of how the regulator has scaled its illegal-market enforcement.
The enforcement scale is funded by an HM Treasury allocation of approximately £26 million over three years to strengthen the UKGC’s anti-illegal-gambling capability. The funding has gone into investigation, technology, and international coordination, all aimed at disrupting the supply of unlicensed gambling to British residents.
The mechanics of illegal-market enforcement are layered. Cease-and-desist notices target operators directly; payment-blocking arrangements with UK financial institutions sever the operator’s ability to take card deposits from British residents; advertising restrictions target the affiliates and search-engine routes that lead punters to unlicensed sites. The combined effect is to raise the cost of operating illegally to British residents to a point where the commercial logic favours either UK licensure or withdrawal from the UK market.
The largest single enforcement challenge has been the crypto route. As Tim Miller of the UK Gambling Commission has put it, illegal-markets research gives the regulator evidence that crypto is one of the two biggest searches that lead British gamblers to illegal sites. The pattern is consistent across cricket and other markets: punters seeking to gamble with crypto find themselves on unlicensed operators because UK-licensed operators do not accept crypto, and the regulator has been explicit about treating the crypto search as an entry point to harm.
For the cricket punter, the enforcement landscape produces two practical realities. First, the operators visibly serving the UK market are licensed because the consequences of operating unlicensed have become substantial. Second, the temptation to use unlicensed operators — typically because they offer products UK-licensed operators do not, including crypto deposits or higher-stake limits — exposes the punter to the absence of every consumer protection the LCCP requires. There is no dispute resolution, no fund segregation, no GamStop integration, and no recourse if the operator fails to pay out.
The enforcement trajectory is one-way. The regulator is scaling its capability, the international coordination is tightening, and the cost to operators of running unlicensed UK-facing operations is rising. Cricket punters who restrict their staking to UK-licensed operators are operating inside the system. Those who do not are operating outside it.
The Statutory Levy and How Cricket Bets Feed It
Every bet placed on a UK-licensed operator now contributes, indirectly, to the funding of NHS gambling-harm treatment services. The mechanism is the statutory Gambling Harms Levy, which took effect in April 2025 with NHS England formally taking on full management of the levy from that date.
The levy replaces the previous voluntary contribution system, under which operators chose how much to give to research, education, and treatment of gambling-related harms. The voluntary system delivered inconsistent funding and was widely criticised as inadequate. The statutory levy is mandatory, set at a percentage of the operator’s gross gambling yield, and earmarked for specific harm-reduction purposes.
The percentage scales with operator type and is highest for the highest-margin gambling sectors. Online betting on real events — which includes cricket — sits in a middle tier. The exact percentage is published by the regulator and the funds are collected centrally and disbursed under NHS England’s management. The operator pays the levy; the punter does not see it as a line item, but it is built into the operator’s cost base and ultimately reflected in the pricing margin the operator publishes.
What this means for cricket markets specifically is that the cost of doing business as a UK-licensed cricket operator has risen — modestly, but measurably — since April 2025. The operator absorbs the levy out of its margin, and competitive pressure prevents the operator from passing the entire cost on through wider prices. But the levy is part of the structural reason that UK-licensed operators publish marginally wider margins on equivalent cricket markets than non-UK operators offering to UK residents through grey-market channels.
For the punter, the levy is invisible but consequential. It funds the NHS treatment capacity that 21.9 percent of UK 18-to-24s — the group with the highest Problem Gambling Severity Index scores — may eventually need. It also funds research into gambling-related harm, public education, and the regulatory infrastructure that supports the integrity network. The levy is the visible financial bridge between the operator’s profit and the social cost of gambling.
The levy also incentivises operators to reduce harm at the operator level. Operators with lower harm rates pay the same percentage, but reducing harm reduces the secondary regulatory costs the operator incurs through enforcement and dispute-resolution. The economic alignment is gradually shifting in favour of operators that build effective player-protection tools, and cricket punters benefit from being on platforms that take those tools seriously.
What Licensing Costs Mean for Cricket Odds You See
The full cost of running a UK-licensed cricket sportsbook has risen materially since the last LCCP revisions. Licence fees, the statutory levy, integrity-monitoring contracts, identity-verification systems, dispute-resolution access, and the compliance staffing that the LCCP effectively requires all sit in the operator’s cost base. The combined cost is the structural reason that UK cricket odds are what they are.
The competitive market shape concentrates that cost. William Hill captured 37.83 percent of paid search click share in the UK sports betting category in early 2026, and William Hill and Bet365 together held more than 50 percent of the search click share. The concentration tells you that the bulk of UK cricket betting flows through a small number of operators, and those operators carry the structural cost base of full UK licensing.
The smaller operators in the UK market face a different problem. They carry the same regulatory cost base as the large operators but spread it across smaller volumes, which means their cost per bet is structurally higher. They respond by either accepting thinner margins to compete, by specialising in markets the large operators do not run well, or by exiting the UK market when the economics no longer work. The exit pattern has accelerated in the past three years.
For the cricket punter, the practical implication is that the operators publishing the deepest cricket books are the same operators with the largest UK market share, and the prices on those operators reflect the cost of operating at scale within the UK regulatory framework. Margins on top cricket markets at the largest UK operators are usually within 0.5 to 1 percent of each other on headline fixtures. Smaller operators may publish marginally better prices on niche markets but rarely beat the major operators on liquidity-driven mainstream markets.
The cost structure also shapes the operator’s product priorities. The high cost base incentivises operators to invest heavily in the products that generate the most revenue per bet — usually bet builders, in-play, and accumulators — and to under-invest in low-margin niche markets such as County Championship props. The cricket punter sees the consequence on the coupon: rich product depth on IPL and Ashes, thin product depth on second-tier domestic cricket.
The closing observation is that the UK cricket pricing you see is the output of a heavily regulated, capital-intensive industrial operation. The price on screen reflects model accuracy, operator margin, regulatory cost, integrity overhead, and competitive pressure. None of those layers are negotiable. The cricket punter who understands them does not necessarily get better prices, but they do get a clearer view of what the prices actually represent.
Practical Signals of a Well-Run UK Cricket Sportsbook
The LCCP creates the regulatory floor. Above the floor, operators vary substantially in how well they run their cricket products. Distinguishing a well-run cricket book from a mediocre one is a skill that pays back over thousands of bets, even when the headline prices look identical.
The first signal is rules clarity. A well-run cricket book publishes detailed settlement rules for every market it runs, with worked examples for edge cases. A mediocre book publishes generic terms and leaves edge cases to be discovered after the dispute arises. Read the operator’s cricket-specific rules page before opening an account; the depth and specificity tell you how seriously the operator takes its product.
The second signal is depth of market menu on competitions the operator covers. A well-run operator carries full menus on IPL, Ashes, ICC events, and The Hundred, with consistent player props across fixtures. A mediocre operator carries deep menus on the headline fixtures and thin menus on the secondary fixtures in the same competition. The inconsistency is a sign of an under-resourced trading desk.
The third signal is pricing consistency across formats. A well-run operator publishes coherent prices across formats — the implied probability on a team across Test, ODI, and T20 should make sense given the team’s relative strength in each format. A mediocre operator publishes formats independently, leading to internal inconsistencies that occasionally produce arbitrage opportunities for sharp punters.
The fourth signal is in-play stability. A well-run operator suspends markets briefly around major events and reopens at sensible repriced lines. A mediocre operator either suspends too aggressively — locking out punters for minutes at a time on routine events — or too rarely, leaving stale prices live during events the engine should have suspended.
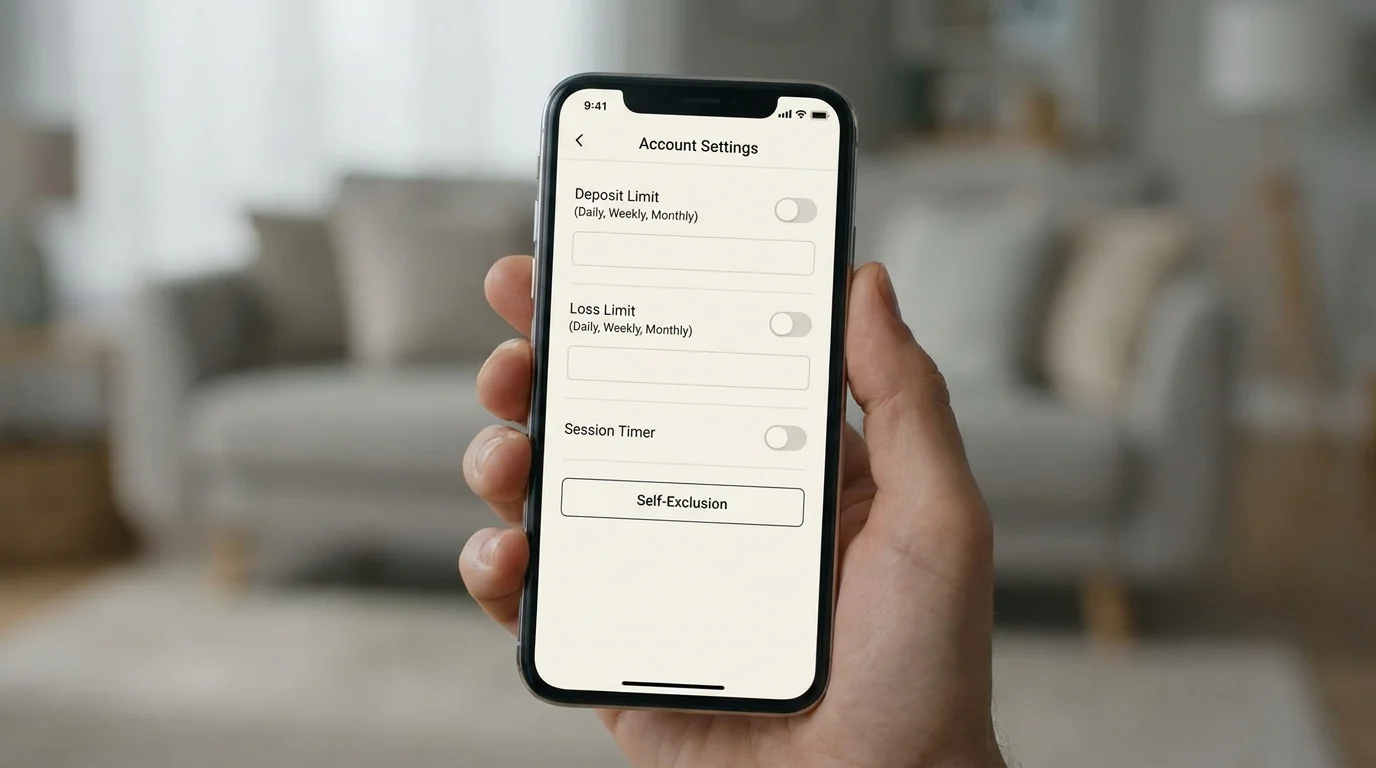
The fifth signal is responsible-gambling tooling. A well-run operator surfaces deposit limits, loss limits, session timers, and self-exclusion prominently in the account interface. A mediocre operator buries them behind multiple clicks. The LCCP requires the tools; the operator’s choice of how to surface them tells you about the operator’s approach to player welfare.
The sixth signal is dispute responsiveness. The LCCP requires every UK-licensed operator to provide alternative dispute resolution and to respond to complaints within published timescales. A well-run operator resolves most disputes internally within days. A mediocre operator escalates to ADR routinely, which is a sign of slow internal processes or a culture of dispute that does not favour the customer.
Licensing and Integrity Reader Questions
The four questions below cover the questions readers ask me most often about UKGC licensing and the integrity framework. They are practical questions with specific answers, not theoretical ones.
How is a UKGC remote licence different from a Gibraltar or Malta licence?
A UKGC remote licence permits the operator to take bets from British residents under the LCCP and full UK regulatory supervision, with all associated consumer protections including GamStop integration, mandatory identity verification, fund segregation, and alternative dispute resolution. A Gibraltar or Malta licence permits the operator to operate under those jurisdictions’ regulatory frameworks and does not authorise taking bets from British residents. An operator licensed only in Gibraltar or Malta cannot lawfully serve UK customers, even if their site is accessible from a UK IP address.
What is the UK Gambling Commission’s Sports Betting Intelligence Unit (SBIU)?
The SBIU is the UKGC’s internal investigation team responsible for betting-integrity matters affecting British markets. The unit receives intelligence from operators, sports governing bodies, and integrity associations including IBIA and Sportradar; investigates patterns of suspicious activity; and coordinates with law enforcement on criminal cases. The SBIU is the British end-point for integrity intelligence flows on cricket and other sports.
How does the IBIA share alerts with UK regulators?
The International Betting Integrity Association operates under information-sharing agreements with national regulators including the UK Gambling Commission. When a member operator detects a suspicious betting pattern on cricket or other sports, the operator files an alert with IBIA, which aggregates the data and routes it to the relevant national regulator and the relevant sports governing body. The UKGC’s SBIU receives IBIA alerts relating to UK-facing operators or events with UK betting implications, and incorporates the alerts into its broader integrity intelligence picture.
Are UKGC-licensed cricket bookmakers required to publish payout figures?
The LCCP does not require operators to publish per-customer or per-market payout figures, but operators are required to report aggregate gross gambling yield and related metrics to the regulator on a quarterly basis. Some operators voluntarily publish summary information on customer outcomes, and the UKGC publishes industry-wide quarterly statistics that aggregate operator returns by sector. Granular per-cricket-market payout data is generally not published, partly because it would expose operator commercial information and partly because it would not meaningfully help customers compare books.
